


Buy the latte: Ways to improve your finances without cutting back on your daily cuppa
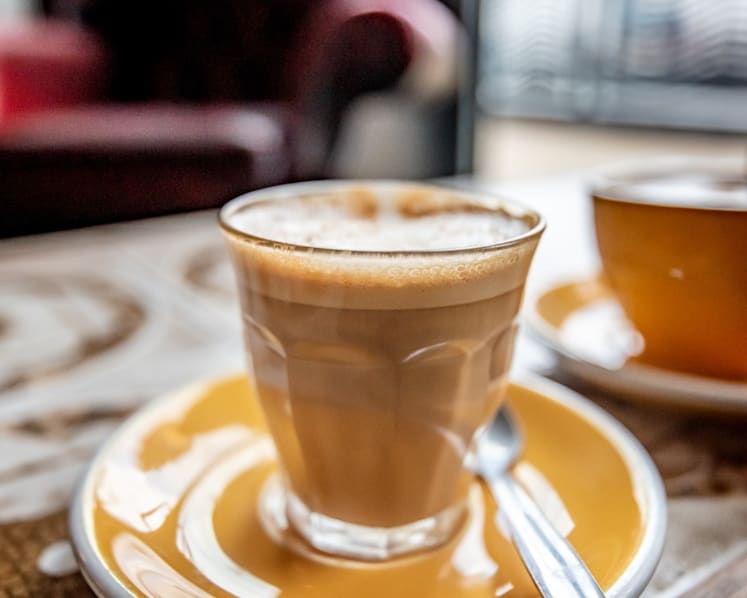
Some financial experts suggest that millennials skip their daily latte and save the money instead so that they can become rich.
Rather than saving S$5 or so several times a week, though, it’s important to focus more broadly on saving, budgeting and investing.
There are plenty of financial advisers suggesting that skipping fancy coffees can put you on the path towards buying a home or having a comfy retirement.
Property website 99.co, for example, suggests that habits you may consider cutting out in order to have enough money to buy a home include “your daily Starbucks coffee fix”.
Chase Bank in the United States advertised this year that a way to build up your bank balance is to “make coffee at home”. And writer David Bach made skipping coffee more famous with his recent book, The Latte Factor.
The challenge with focusing just on these special brews is that simply skipping a coffee every day would be unlikely to give you enough to reach your goals.
If you skip a $5 coffee 20 days a month and put S$100 a month in a time deposit earning 1.5 per cent interest a year, for example, you will have S$27,968 after 20 years.
Even if you put it in an exchange-traded fund (ETF) that invests in stocks and earn 5 per cent, you’ll still only end up with S$41,103.
While it is a nice sum of money, it is clearly not enough to buy a house or retire.
A BETTER WAY TO SAVE
If saving small amounts takes the fun out of life and you’re grumpier because you’re not getting your usual coffee every morning, it would make it harder to save.
Those small purchases, including going to a nice cafe and drinking the latte, may have meaning and perk you up.
Indeed, the Twitter backlash about Chase Bank’s ad was so bad that it had to back down.
Instead of just giving up small treats, it is more important to look at the big picture and figure out how to save enough to reach your goals.
For a start, put together a list of everything you are spending during the month. It may turn out that you are wasting money and don’t realise it.
A study in the US by market research company OnePoll, for example, showed that Americans spend nearly US$1,500 (S$2,062) a month on non-essentials ranging from eating out and food delivery to streaming services and subscription boxes. While the total may be lower here, figuring out what and where you spend may help identify spending that you don’t really need. You can cut out expenses that don’t matter much.
Insurance firm Singlife suggests, for example, that you can cut back on food waste by using a list to buy groceries once a week, have a kopi at the neighbourhood coffee shop sometimes rather than a fancy latte, eat at hawker centres rather than restaurants and take the bus rather than a rideshare.
PUT UP A BUDGET
Next, develop a budget that shows your total income and expenses — after you have taken out those non-essential items.
You can then use a budgeting application such as Toshl or a digital worksheet to track your income and expenses every day.
An essential part of that budget is saving. While a simple guideline is to save 10 to 20 per cent of your salary, national financial education portal MoneySense suggests that “it really depends on how fast you’d like to reach financial freedom”. Bumping it up to 15 to 25 per cent will get you to your goals faster. And putting the money into a separate savings or investing account can help make sure you don’t spend it.
While it may seem hard to save that much, checking your spending again can help you decide what to cut out and how to save more.
If coffee is not as important as you thought, skipping it could help. There are also likely to be other purchases that you could just as easily do without.
Still, including small amounts for treats in your budget can help you feel better about occasional indulgences.
GET YOUR MONEY WORKING
Then, invest your money well to earn a higher return.
If your income is around the Singapore median of S$2,792 a month and you save 20 per cent, or S$558 monthly, earning 1.5 per cent on a time deposit would give you about S$156,064 after 20 years.
Raise the return to 3 per cent and you’ll have S$183,192. Putting it in stocks and getting a 5 per cent return could get you S$229,356.
An easy way to do that is to use an automatic investment into ETFs through services such as POSB Invest-Saver or the OCBC Blue Chip Investment Plan.
The ABF Singapore Bond Index Fund averaged a return of 2.16 per cent a year over the past five years, for example, and 2.75 per cent since it started in 2005.
The Nikko AM Singapore STI ETF that invests in stocks averaged an average of 6.58 per cent a year over the past three years and 9.43 per cent since it was established in 2009.
While just skipping the lattes won’t be enough to get you to your goal, taking time to put together a budget and figuring out large amounts that you can skip in order to invest can put you on the path towards the financial freedom you really want.